Table of Contents
Buying a condominium on O‘ahu means reviewing more than the unit itself. You also need a clear picture of the association that owns and maintains the common elements. The Hawai‘i Association of REALTORS Property Information Form, commonly called the RR105c, is one of the most important documents in that process. Completed by the managing agent at the seller’s request, it summarizes current facts about the project’s legal structure, insurance, finances, and physical condition.
A careful review of the RR105c and the accompanying condo document package can reveal issues that affect your monthly costs, financing eligibility, and long-term ownership experience. This guide explains the review process, highlights common red flags, and shows how we help buyers identify issues that could affect financing, costs, or long-term ownership.
What the RR105c Covers
The RR105c is a multi-page form organized into four main sections:
General & Legal
Insurance
Financial
Project Condition
It reports the total number of units, approximate owner-occupancy percentage, guest parking, leasehold or fee-simple status, delinquency rates, special assessments, pending litigation, insurance coverage details, what maintenance fees include, and whether a current reserve study exists. Because the form must be dated close to the transaction, it reflects conditions at the time of the sale rather than a static historical record.
Lenders also rely on this form (or a companion lenders’ disclosure) when underwriting condo loans. High delinquencies, litigation affecting structure or safety, or inadequate reserves can make a project non-warrantable for conventional financing.
The Condo Document Review Timeline on O‘ahu
Under Hawai‘i law, when the property is subject to a recorded declaration, the seller must deliver the governing documents (declaration, bylaws, house rules, and related materials) within a set window after the title report is received. Buyers then have a review period, often 10 to 15 days in the standard purchase contract, to examine everything and decide whether to proceed, negotiate, or cancel.
The full package typically includes:
Declaration and any amendments
Bylaws and house rules
Current budget and financial statements
Reserve study or summary
Recent board meeting minutes
Insurance certificate or summary
RR105c and any statement of account
We recommend starting with the RR105c for an overview, then cross-checking the numbers against the financials, reserve study, and minutes. Professional legal or accounting review is available and often worthwhile for larger or older projects.
Red Flags in the RR105c and Supporting Documents
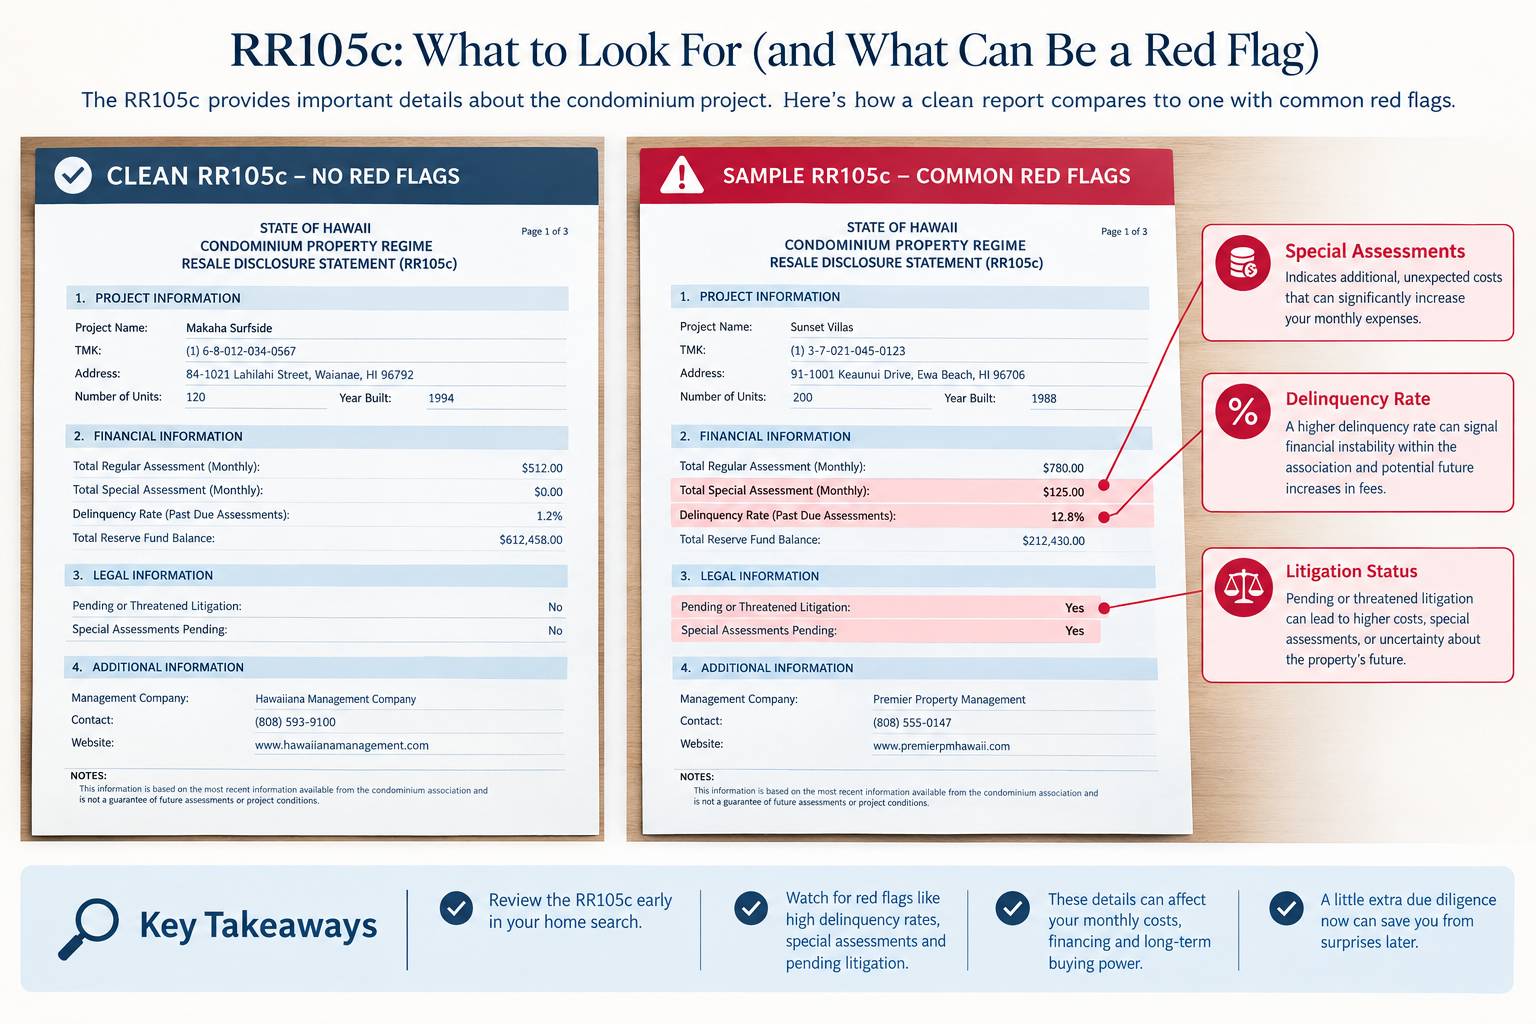
Not every “yes” answer is a deal-breaker, but certain patterns deserve extra scrutiny. The table below summarizes frequent warning signs and why they matter.
Area | Potential Red Flag | Why It Matters |
|---|---|---|
Financial | High delinquency rate (especially units 60+ days past due) | Can signal weak collections and future special assessments; may affect lender approval |
Financial | Thin or underfunded reserves relative to building age and planned projects | Increases likelihood of large one-time assessments for roofs, elevators, or structural work |
Financial | Existing or planned special assessments | Adds unexpected cost that transfers to the new owner |
Legal | Pending or recent litigation involving the association | Can delay financing, raise insurance costs, or create future liability |
Legal / General | Low owner-occupancy percentage | May affect financing eligibility and day-to-day community stability |
Insurance | Gaps in coverage or high deductibles for hurricane, flood, or liability | Leaves owners exposed to large out-of-pocket costs after an event |
Project Condition | Deferred maintenance noted without a clear funding plan | Points to future assessments or declining building condition |
General | Single-entity ownership of a large percentage of units | Can influence board decisions and financing guidelines |
Cross-reference any concerning answers with the reserve study, recent board minutes, and financial statements. Minutes often reveal discussions that have not yet appeared on the formal disclosure form.
How We Approach Document Review Differently
At Hawai‘i Modern Realty, we help buyers organize the condo document package and focus on the information most relevant to their purchase, financing, and intended use. Our advisors regularly work with buildings in Waikīkī, Ala Moana, Kaka‘ako, and neighborhoods across the island. We help buyers review association finances, building maintenance concerns, and project-specific information that may affect financing or ownership costs. When lender requirements or legal questions arise, we coordinate with the appropriate lender or professional advisor.
We help organize the documents and focus your review on items that can affect your budget, financing, and intended use of the property. Personalized guidance means we walk through the RR105c and supporting files with you, flag items that matter for your financing or intended use (primary residence, second home, or investment), and coordinate with your lender or attorney when needed.
Our role is to help you identify questions early, understand which documents need closer review, and coordinate with your lender or other professionals when needed.
Practical Steps for Buyers
Request the complete package as soon as the contract allows.
Read the RR105c first for the high-level summary.
Compare maintenance-fee inclusions, delinquency figures, and assessment disclosures against the budget and reserve study.
Scan the last 12 months of board minutes for recurring complaints or planned capital projects.
Confirm insurance coverage meets your lender’s requirements.
Ask clarifying questions early so answers arrive inside the review window.
If you are financing, share the RR105c and related forms with your lender promptly. Financing contingencies and document-review deadlines often run on parallel clocks.
Areas We Serve and Property Expertise
Hawai‘i Modern Realty works across the islands with particular strength on O‘ahu. Our advisors regularly assist clients with:
Condominiums and high-rise residences in Waikīkī, Ala Moana, and Kaka‘ako
Townhomes and mid-rise projects in Kapolei, ‘Ewa Beach, and Central O‘ahu
Luxury homes and ocean-view properties in Kailua, Hawai‘i Kai, and surrounding communities
Investment and rental properties statewide
Open-house coordination and off-market opportunities
Whether you are purchasing your first condo, relocating, or adding an investment unit, we match the right local advisor to your goals.
Useful Tool for Your Purchase Planning
Before you finalize an offer or adjust your budget after reviewing association fees and possible assessments, run the numbers with our Mortgage Payment Calculator. It helps you estimate monthly principal, interest, taxes, and insurance so you can see how maintenance fees and any special assessments fit into your overall picture.
Frequently Asked Questions
What is the RR105c and who prepares it?
The RR105c is the Hawai‘i Association of REALTORS Property Information Form for condominiums, co-ops, and similar associations. The managing agent completes it based on current association records at the seller’s request.
How current must the RR105c be?
Lenders and buyers generally expect a form dated close to the transaction date, often within 30 days. Older forms may need updating.
Can high delinquencies stop my loan?
Yes. Conventional lenders often have thresholds for the percentage of units past due. Exceeding those thresholds can make the project non-warrantable.
What if the reserve study shows underfunding?
You can still proceed, but you should understand the likelihood of future special assessments and factor that risk into your offer or budget.
Do I need a lawyer to review the documents?
We are not attorneys or accountants. For complex projects or large purchases, many buyers choose independent legal or financial review in addition to the guidance we provide.
How long do I have to review the condo documents?
The purchase contract sets the review period, commonly 10–15 days after delivery of the required documents. Confirm the exact timeline in your agreement.
Ready to Review Your Next O‘ahu Condo with Confidence?
The RR105c and the full document package give you a window into the association’s health before you close. Taking the time to understand the numbers, ask the right questions, and compare them against the reserve study and minutes protects both your investment and your peace of mind.
If you are exploring condominiums on O‘ahu or elsewhere in Hawai‘i, connect with a Hawai‘i Modern Realty advisor. We will help you request the right documents, interpret the key disclosures, and move forward with clarity. Reach out today to start a conversation about your goals.